atisusanti
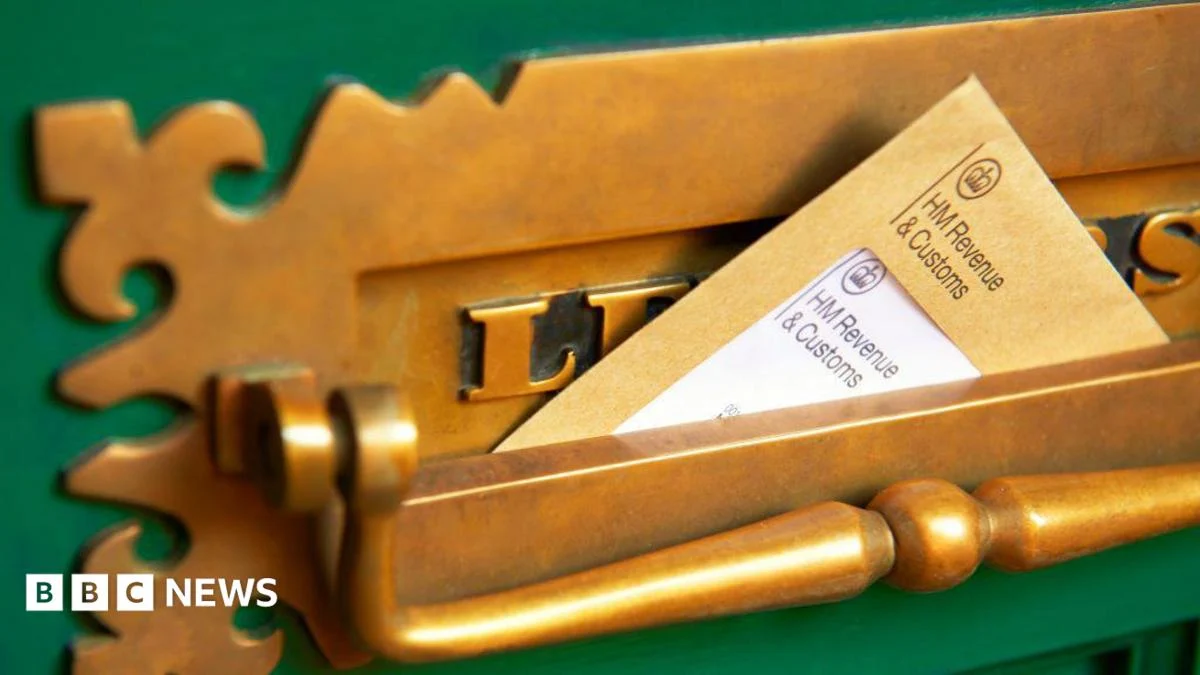
HM Revenue and Customs (HMRC) has launched a significant crackdown on cryptocurrency tax evasion, sending a staggering 81,172 warning letters to individuals suspected of owing capital gains tax on their digital asset holdings in the 2025-26 financial year. This represents a dramatic surge, with the number of such letters nearly tripling from the 27,714 issued in the preceding 2023-24 period. The tax authority’s intensified efforts underscore a growing concern that a substantial amount of tax revenue from the booming cryptocurrency market remains undeclared. Investors who fail to report profits from selling or even exchanging one cryptocurrency for another could face severe penalties, including hefty fines and, in more serious cases, potential prosecution.
The looming introduction of new powers for HMRC next year is set to significantly enhance its ability to identify and pursue wealthy crypto investors. Experts predict that these forthcoming capabilities will transform tax investigations into the sector, with one analyst describing the process as akin to "shooting fish in a barrel." Neela Chauhan, a partner at UHY Hacker Young, the firm that conducted the Freedom of Information (FOI) request revealing these figures, highlighted the prevalent sentiment among tax authorities. "There is the expectation amongst tax authorities that cryptocurrency investment is rife with tax evasion," Ms. Chauhan stated. She further elaborated on the profile of many crypto traders, noting, "A lot of the traders are young, have had little previous exposure to HMRC and often work under the assumption that HMRC has limited visibility over their activities." This perceived lack of oversight, however, is rapidly diminishing.
The surge in warning letters comes despite a recent downturn in the value of major cryptocurrencies like Bitcoin and Ethereum over the past year. HMRC’s concern stems from the substantial capital gains accrued by investors during a period of unprecedented price appreciation in the cryptocurrency market. Specifically, HMRC is scrutinizing gains made between December 2022 and October 2025, a period during which Bitcoin experienced a remarkable ascent, with its price skyrocketing from approximately £14,000 to as high as £90,000. While the market has since cooled, with Bitcoin currently trading around £48,000, the profits generated during the boom are now firmly in HMRC’s sights.
In response to the burgeoning number of warning letters, an HMRC spokesperson reiterated the department’s commitment to ensuring tax compliance. "We’re committed to helping people pay the right amount of tax, and the vast majority do," the spokesperson said. "We regularly send letters to educate, remind or prompt customers to review their tax affairs, including customers who use crypto assets." This proactive approach aims to bring crypto investors into the tax system, preventing the accumulation of undeclared liabilities.
Accountants are strongly advising cryptocurrency investors to proactively review their holdings and tax obligations. The impending legislative changes are designed to equip HMRC with unprecedented access to information, making it considerably more difficult for individuals to conceal their crypto-related profits. From March 2027, a significant shift in international data sharing protocols will come into effect. Cryptocurrency platforms operating in dozens of countries outside the UK will be legally obligated to share comprehensive data about their customers with tax authorities, including HMRC. This global cooperation is a key component of HMRC’s strategy to combat offshore tax evasion and ensure that digital asset investors are held to the same tax standards as those investing in traditional assets.
When these new powers were initially announced last year, HMRC explicitly stated their intention to compel "crypto bros to pay their fair share of tax." The department has projected that these enhanced data-gathering capabilities will generate an estimated £315 million in additional tax revenue by April 2030. This figure has been contextualized by HMRC as being equivalent to the annual funding required for over 10,000 newly qualified nurses, underscoring the significant financial implications of crypto tax evasion.
The prospect of HMRC gaining such comprehensive access to cryptocurrency transaction data has led to widespread concern among tax professionals and crypto investors alike. Ms. Chauhan’s earlier warning about investigations becoming "like shooting fish in a barrel" encapsulates the anticipated shift in the enforcement landscape. With detailed transaction histories readily available, HMRC will be able to conduct highly targeted and efficient investigations, identifying undeclared gains with a significantly lower margin of error. This will likely lead to a substantial increase in the number of individuals identified as having underpaid tax, resulting in a wave of penalties and compliance actions.
The capital gains tax implications for cryptocurrency investors are often complex. When an investor sells a cryptocurrency for a profit, they are generally liable for capital gains tax on that profit. This applies whether the profit is taken in fiat currency (like pounds sterling) or exchanged for another cryptocurrency. Even swapping one digital asset for another can trigger a taxable event, as it is considered a disposal of the original asset. The calculation of capital gains tax involves determining the cost basis of the asset and subtracting it from the proceeds of the sale. For individuals who have engaged in numerous transactions, or held assets for extended periods, accurately tracking these figures can be a significant challenge, and a common source of unintentional tax errors.
Furthermore, the tax treatment of cryptocurrencies can vary depending on how they are held and used. For example, profits from mining or staking activities may be subject to income tax, while gains from selling or exchanging cryptocurrencies are typically subject to capital gains tax. The evolving nature of the crypto market, with new tokens, decentralized finance (DeFi) protocols, and non-fungible tokens (NFTs), presents ongoing challenges for both investors and tax authorities in understanding and applying the relevant tax rules. HMRC’s increased focus suggests a commitment to adapting its enforcement strategies to keep pace with these developments.
The proactive approach of sending warning letters serves a dual purpose. Firstly, it aims to educate crypto holders about their tax obligations and the potential consequences of non-compliance. Secondly, it acts as a strong signal that HMRC is actively monitoring the sector and possesses the means to identify those who are not meeting their tax responsibilities. For many young investors who may have entered the crypto market with limited understanding of traditional tax frameworks, these letters are a crucial wake-up call.
The significant increase in warning letters and the introduction of new international data-sharing powers signal a new era for cryptocurrency taxation in the UK. Investors are strongly advised to engage with tax professionals, meticulously record all their cryptocurrency transactions, and ensure that all capital gains are declared accurately and on time to avoid potentially severe financial penalties and legal repercussions. The message from HMRC is clear: the era of cryptocurrency tax evasion is rapidly drawing to a close, and compliance is no longer an option but a necessity. The department’s resolve to capture lost tax revenue is evident, and its capabilities are set to expand dramatically in the near future.

 Roy Suryo
 George Anjay
 Nakalama John
 Ramos Leo