
 Ramos Leo
The Bank of England has maintained its main interest rate at 3.75% for the sixth consecutive meeting, a decision that underscores the delicate balancing act faced by policymakers amidst persistent inflationary pressures and a volatile global economic landscape. Despite this pause, the central bank issued a stark warning: rates are highly likely to increase if the elevated energy prices, primarily triggered by escalating geopolitical tensions and conflict in the Middle East, continue to bite. This conditional forward guidance signals the Bank’s unwavering commitment to its inflation target, even as it navigates an environment fraught with uncertainty.
The decision to hold rates comes despite a recent uptick in the UK’s inflation rate. Official figures released on Wednesday revealed that the Consumer Prices Index (CPI) rose to 3.1% in August, up from 2.9% in July. While this remains above the Bank’s 2% target, the Monetary Policy Committee (MPC) opted for a cautious approach, acknowledging the lagged effects of previous rate hikes and the unpredictable nature of external shocks. The current rate of 3.75% is a crucial benchmark, influencing everything from mortgage rates and business loans to the returns on savings accounts across the UK economy.
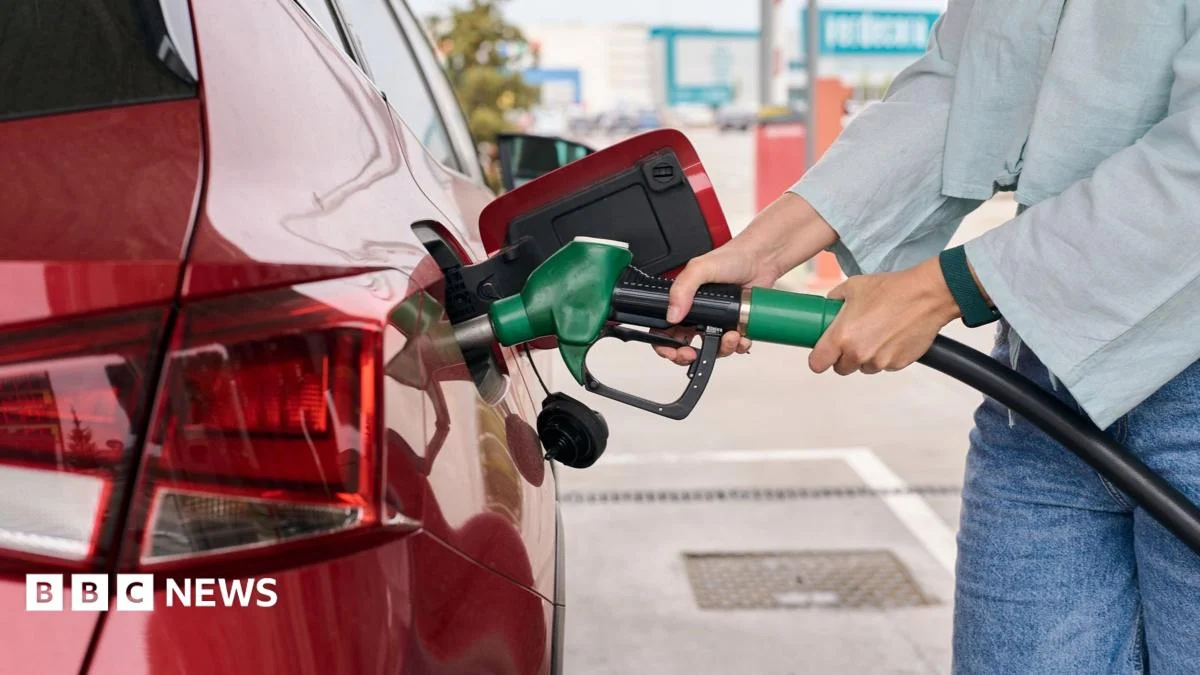
A primary driver behind the Bank’s cautionary stance is the severe disruption to global energy supplies. The intensifying conflict involving the US, Israel, and Iran has cast a long shadow over international oil and gas markets, leading to a sharp and sustained increase in the wholesale prices of crude oil and natural gas. This has directly translated into higher costs at the pump for motorists, with petrol and diesel prices surging, and is expected to exert significant upward pressure on household energy bills in the coming months.
Speaking after the MPC’s decision, Bank of England Governor Andrew Bailey articulated the gravity of the situation. He emphasized that the longer the current volatility in energy prices persists, "the bigger the impact it will have on inflation and the more likely it is we will need to raise [the] Bank rate to ensure that inflation falls back to our 2% target." This statement highlights the Bank’s primary mandate: to ensure price stability. The direct impact of higher energy costs on headline inflation is undeniable, but officials are also closely monitoring how these costs might feed into wider inflationary pressures across the economy, potentially becoming embedded in wages and other prices.
The Bank’s latest forecasts reflect this deepening concern. It now predicts that inflation will rise more significantly than previously anticipated. Furthermore, the energy price cap, which limits the average cost of household gas and electricity bills, is "now expected to rise substantially further" for January, threatening to add considerable strain to household budgets already grappling with a cost-of-living crisis. This anticipated increase underscores the direct and immediate impact of geopolitical events on everyday consumers in the UK.
The UK’s central bank uses interest rates as its primary tool to manage inflation, influencing the cost of borrowing and the incentive to save. When inflation rises above its 2% target, the Bank typically considers raising rates to cool demand in the economy, thereby reducing the upward pressure on prices. Conversely, lower rates can stimulate economic activity. The UK has seen inflation above the target for nearly two years, prompting the series of rate hikes that preceded the current pause.
Globally, other major central banks have been more aggressive in tightening monetary policy to counteract higher prices. On Wednesday, the US Federal Reserve announced its first interest rate hike in three years, signaling a shift towards a more hawkish stance. Similarly, the European Central Bank (ECB) has raised rates twice since June, reflecting a broad international effort to tame inflation. These synchronized global actions indicate a shared concern among central bankers about the stickiness of inflation and the need to restore price stability.
The MPC’s vote on the latest decision revealed a split among its nine members. Six members voted to maintain the Bank rate at 3.75%, opting for a wait-and-see approach. However, three members, including the Bank’s chief economist Huw Pill, dissented, advocating for an immediate quarter-point increase to 4%. This split highlights the ongoing debate within the committee regarding the appropriate timing and pace of monetary tightening, weighing the risks of over-tightening against the risks of allowing inflation to become entrenched. Those voting for a hike likely believe that proactive measures are necessary to prevent inflation expectations from becoming unanchored.
Financial markets have largely priced in the possibility of several further rate rises next year, reflecting the prevailing expectation that inflation will remain a challenge. However, Governor Bailey cautioned that the global backdrop remains "hugely unpredictable at the moment." He emphasized that for interest rates to meaningfully come down, a significant de-escalation of the conflict in the Middle East and a return of energy prices to pre-conflict levels would be necessary. This underscores the external, non-monetary factors that heavily influence the Bank’s policy decisions.
Despite the prevailing challenges, the Bank of England did offer some glimmers of optimism regarding the UK economy. It noted that the economy has proven "more resilient" than initially expected, revising its forecast for economic growth between July and September upwards to 0.4%, a notable improvement from the 0.1% increase it had predicted in the summer. This suggests some underlying strength in economic activity, potentially driven by robust consumer spending or a resilient labor market.
Furthermore, the Bank indicated that the full effect of higher energy costs has not yet spilled over into other areas of the economy as much as feared. Consequently, its forecast for food price inflation by the end of the year has been revised downwards to 4%, a significant reduction from its previous projection of 6-7%. This suggests that some of the global supply chain pressures that contributed to food price increases may be easing, offering some relief to consumers.
For households, a rising Bank rate directly translates into higher borrowing costs, particularly for those on variable-rate mortgages or those seeking new fixed-rate deals. Mortgage rates have already been on an upward trajectory. According to financial information service Moneyfacts, the average two-year fixed residential mortgage rate reached 5.77%, its highest since May 11, while the average five-year fixed rate hit 5.83%, its highest since November 8, 2023. Ahead of the latest decision, Andrew Montlake, chief executive of mortgage broker Coreco, warned that "if inflation proves sticky, lenders’ funding costs stay under pressure, which makes cheaper mortgages harder to deliver." Conversely, savers can benefit from more generous returns on their deposits, though these gains are often eroded by the higher cost of living. Businesses also face increased borrowing costs, which can impact investment decisions and ultimately filter through to consumer prices.
In a separate but equally significant announcement alongside the interest rate decision, the Bank also revealed a major overhaul of its "quantitative tightening" (QT) programme. This involves pausing its annual sales of government bonds – a form of IOU traded on financial markets – and instead opting to sell off smaller chunks over an extended period of eight years. This marks a notable shift in the Bank’s strategy for unwinding the massive bond holdings accumulated during periods of economic turbulence, known as "quantitative easing" (QE).
During the global financial crisis and the Covid-19 pandemic, the Bank purchased £895 billion worth of mainly government bonds to inject liquidity into the financial system, lower long-term interest rates, and stimulate the economy. Since 2022, it has been gradually offloading these bonds through a process of QT, which involves both allowing bonds to mature without reinvestment and active sales. This process contributes to higher interest rates, or yields, on government bonds, making it more expensive for the government to borrow money.
The Bank stated that discussions to reduce its current £488 billion stockpile of bonds began a year ago, implying that this new plan is a strategic adjustment rather than a direct response to recent market volatility. However, the timing is notable given the recent global surge in government bond yields, driven by worries that high inflation, exacerbated by the oil price surge since the Iran conflict, will necessitate higher interest rates worldwide. The news of the Bank of England overhauling its QT programme prompted an immediate and positive reaction in bond markets. The yield on 30-year UK government bonds fell from 5.86% to 5.75% following the announcement, while yields on 10-year bonds dropped from 5.31% to 5.22%. Lower bond yields translate to lower borrowing costs for the government, offering a degree of financial relief.
The Bank of England’s latest decisions reflect a cautious yet resolute approach to monetary policy. While holding rates for now, it has clearly signaled its readiness to act if inflationary pressures, particularly from energy prices, persist. The simultaneous adjustment to its QT programme further illustrates the Bank’s nuanced strategy to manage both short-term interest rates and the broader financial conditions impacting the UK economy, all with the ultimate goal of bringing inflation back to its 2% target. The path ahead remains highly dependent on geopolitical developments and their impact on global energy markets.

 Nana Banana
 Nakalama John
 Roy Suryo
 atisusanti
 George Anjay
