
 Nakalama John
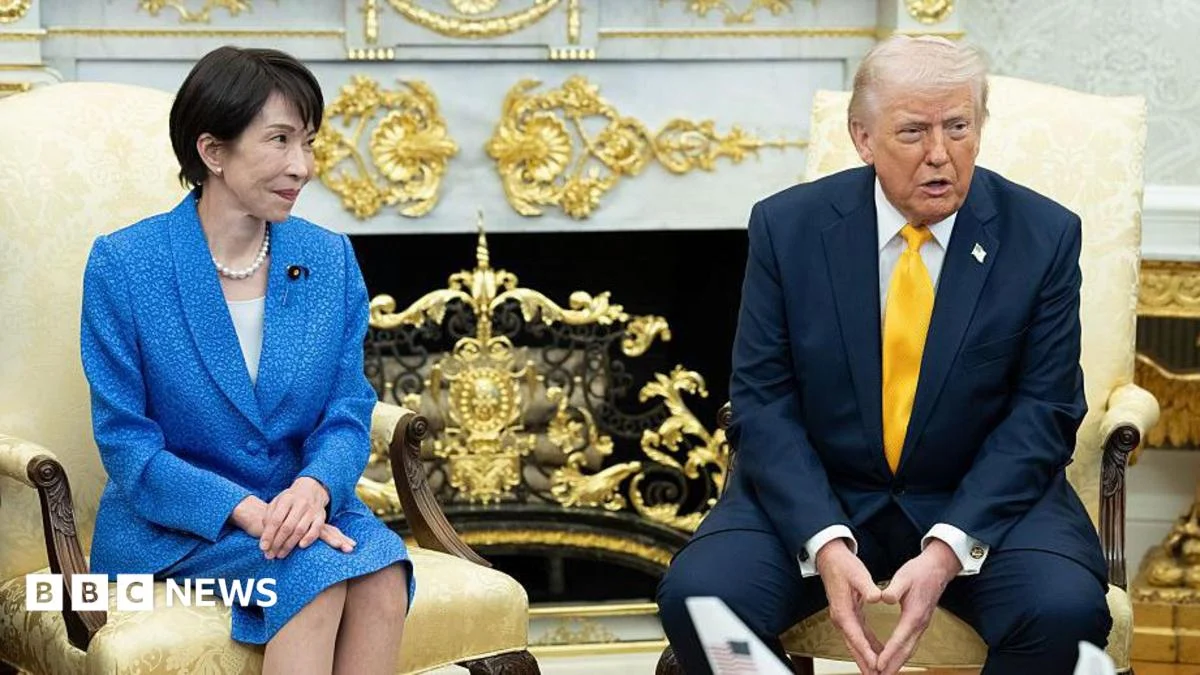
The decision to intervene underscores deep concerns in both Tokyo and Washington regarding the yen’s rapid depreciation. For Japan, a weaker yen inflates import costs, exacerbating inflationary pressures in a nation already grappling with an aging population and structural economic challenges. For the US, an overly strong dollar, partly a consequence of the yen’s weakness, can hurt American exports and potentially complicate the Federal Reserve’s fight against domestic inflation by making imports cheaper.
The previous joint intervention in 2011 was under dramatically different circumstances. Following the devastating Great East Japan Earthquake and tsunami, global financial markets reacted with a surge of risk aversion, leading to a sharp appreciation of the yen as investors repatriated funds to Japan. At that time, the coordinated action by the G7 nations, including the US, aimed to weaken the yen, preventing it from harming Japan’s export-dependent economy during a critical recovery period. The current intervention, however, targets the opposite: to strengthen the yen and prevent further depreciation. This stark contrast highlights the evolving nature of global economic challenges and the flexibility required in international monetary policy.
Both Japan’s finance ministry and US Treasury Secretary Janet Yellen have issued strong statements, indicating their resolve to conduct further joint interventions should market conditions warrant. This forward-looking commitment is a crucial element of their strategy. By signaling their willingness to act repeatedly and in concert, they aim to inject a persistent sense of vigilance into the market, thereby deterring speculative short-selling of the yen. The psychological impact of such a warning can be as potent as the actual amount of currency exchanged during an intervention.
The intervention highlights both countries’ concerted efforts to prevent a destabilizing sell-off in the yen and Japanese government bonds (JGBs) from cascading into broader global economic instability. A disorderly decline in the yen could trigger capital flight from Japan, potentially disrupting global financial flows. Furthermore, a significantly weaker yen contributes to a stronger dollar, which can indirectly push up borrowing costs for Washington by making US assets comparatively more expensive and increasing the cost of servicing dollar-denominated debt for other nations, potentially leading to global financial stress.
Shigeto Nagai, head of Japan economics at Oxford Economics, articulated the strategic benefits of the US participation to the BBC. He noted that "The United States agreed to participate in the coordinated intervention because it serves its national interests by offering the prospect of significant benefits at a low cost." These benefits include fostering global financial stability, mitigating inflationary pressures in the US by curbing dollar strength, and preserving the economic health of a key geopolitical ally. The cost, in terms of the actual dollar amount spent on intervention, is often relatively small compared to the potential economic fallout of unchecked currency volatility.
Experts anticipate that the two countries will continue to intervene "intermittently in a coordinated manner for some time." This intermittent approach ensures that speculators cannot easily predict the timing or scale of interventions, keeping them on edge. "Even if the actual amount of intervention is not particularly large, the prolonged sense of vigilance regarding intervention will be effective in deterring speculators," Nagai added. This strategy aims to create an environment of uncertainty for those betting against the yen, making such trades riskier and less appealing.
The fundamental reason behind the yen’s historical weakness primarily stems from the vast divergence in central bank interest rates between Japan and other major economies, particularly the United States. The Bank of Japan (BoJ) has maintained an ultra-loose monetary policy for years, including a negative interest rate policy and yield curve control (YCC), to stimulate sluggish domestic demand and combat deflationary pressures. While the BoJ did raise its main rate to 1% in June – its highest level since September 1995 – this move was relatively modest and still leaves Japan’s rates significantly lower than its peers. In stark contrast, the US Federal Reserve has aggressively hiked its benchmark rate, which currently stands in a range of 3.50% to 3.75%, in its determined fight against persistent inflation.
This substantial interest rate differential creates a powerful "carry trade" incentive. International investors borrow in yen at low interest rates, convert the funds into dollars, and invest in higher-yielding US assets. This constant selling of yen and buying of dollars drives down the yen’s value. As long as the BoJ maintains its dovish stance while other central banks remain hawkish, this fundamental pressure on the yen is likely to persist.
Beyond monetary policy, Japan also faces deeply entrenched structural challenges contributing to its currency’s long-term depreciation. A decades-long slide in its working-age population presents a formidable demographic headwind, impacting economic growth potential and productivity. Low productivity, a persistent issue, further dampens the economy’s attractiveness. Moreover, Japan’s heavy reliance on energy and commodity imports, which are predominantly priced in US dollars, means that a weaker yen translates directly into higher import costs, exacerbating its trade deficit and putting further downward pressure on the currency.
On Monday, Japan’s finance ministry released a statement affirming that Friday’s coordinated intervention with the US Treasury Department "countered excessive volatility and disorderly movements in the Japanese yen in recent months." This language is critical, as governments typically intervene not to target a specific currency level, but to address "disorderly" market conditions that they deem detrimental to economic stability. Such conditions often include rapid, one-sided movements driven by speculation rather than economic fundamentals.
US Treasury Secretary Janet Yellen echoed this sentiment in a social media post, stating that the "coordinated foreign exchange actions countered disorderly yen movements." She went further, adding, "We strongly support Japan’s decisive market and monetary steps to correct the substantial undervaluation of the yen." The explicit acknowledgment by the US of the yen’s "substantial undervaluation" is a significant diplomatic signal, indicating a shared assessment of the currency’s predicament and legitimizing Japan’s efforts to support it.
A White House spokesperson, affirming the strong US commitment to its ally, Japan, conveyed the sentiment that the US is always there to offer support when needed. This highlights the enduring strength of the US-Japan alliance, extending beyond geopolitical and security concerns to encompass critical economic cooperation. The joint intervention serves as a tangible manifestation of this strategic partnership, underscoring a shared interest in maintaining global economic stability.
In the immediate aftermath, the intervention provided some temporary relief, helping the yen pare back some of its recent losses. However, analysts caution that while interventions can stem rapid declines and deter speculators in the short term, they rarely reverse fundamental currency trends driven by significant interest rate differentials or structural economic issues. For a sustained recovery of the yen, many economists believe that a shift in the Bank of Japan’s ultra-loose monetary policy or significant improvements in Japan’s economic fundamentals would be required.
The rare joint intervention by the US and Japan marks a pivotal moment in global currency markets. It signals a renewed commitment to international coordination in addressing currency volatility and underscores the intricate web of economic dependencies that bind the world’s major economies. While the immediate impact is a stabilization of the yen, the long-term effectiveness will hinge on whether it can buy Japan time to address its underlying economic challenges and whether global monetary policies begin to converge, reducing the powerful forces currently weighing on the Japanese currency. The world will be watching closely for further coordinated actions and shifts in economic policy from both Tokyo and Washington.

 atisusanti
 Nana Banana
 George Anjay
 Ramos Leo
