 Nakalama John
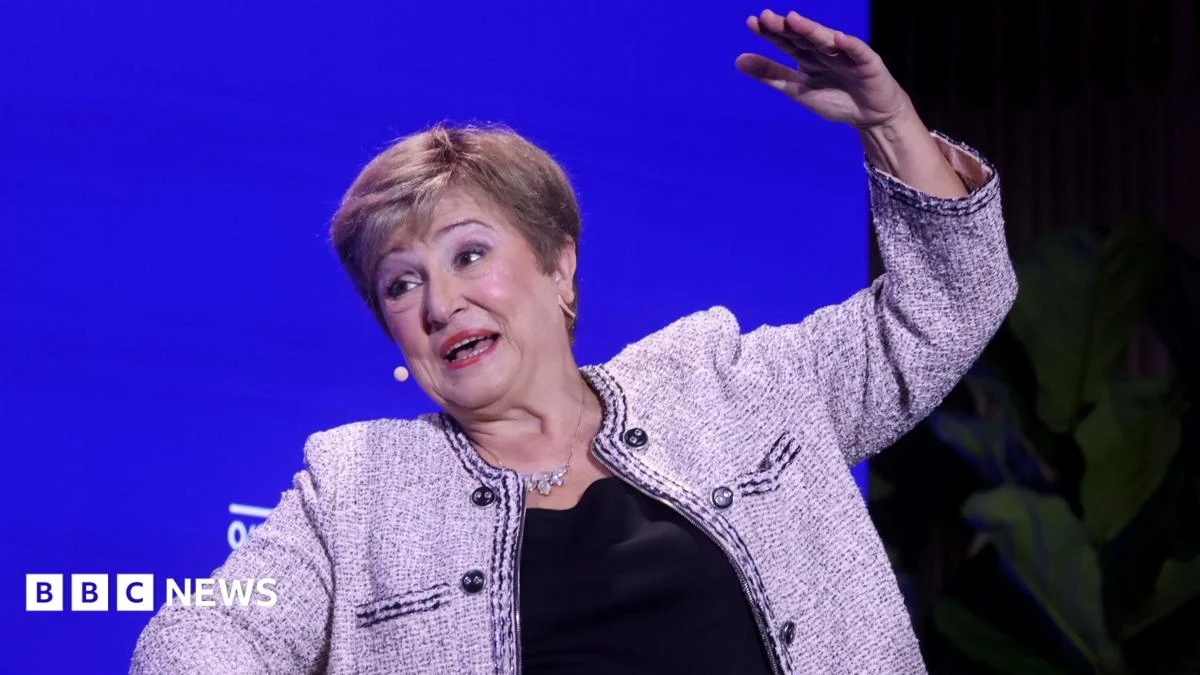
"It’s time to take that action," she asserted, underscoring the immediate necessity for political leaders to demonstrate "courage" in implementing the requisite, albeit potentially unpopular, measures. This significant intervention from the IMF comes at a crucial juncture, as government borrowing costs globally have surged dramatically. This surge is largely a direct consequence of ongoing geopolitical conflicts, particularly those disrupting critical oil supply chains, which have, in turn, fueled persistent and elevated inflation across many economies. Higher global borrowing costs present a formidable challenge, impacting not only national treasuries but also businesses and households as the cost of capital rises across the board.
The repercussions of these elevated borrowing costs are particularly acutely felt in the UK, especially in the crucial period leading up to UK Prime Minister Andy Burnham’s inaugural Budget, anticipated next month. With a new administration often seeking to establish its fiscal credibility and set a clear economic direction, the prevailing environment of high interest rates places immense pressure on the Prime Minister and his Treasury team. Speculation is rife regarding the potential scope and nature of forthcoming tax and spending policies, with difficult choices likely needing to be made to demonstrate fiscal responsibility while attempting to stimulate growth and address public services. Observers anticipate a delicate balancing act, as the government navigates the political implications of potential austerity measures against the economic imperative to rein in borrowing.
Recent official figures starkly illustrate the UK’s fiscal predicament. Government borrowing – representing the fundamental difference between the Treasury’s tax receipts and its total spending – reached a substantial £18.3 billion ($24.4 billion) in August. This figure represented an almost fifth higher than the corresponding period in the previous year, significantly exceeding even official forecasts. The implications of such elevated borrowing are profound, signaling a persistent reliance on debt to fund public services and investments. Furthermore, the debt interest payments recorded for August were the highest figure for that month since detailed monthly records commenced in 1997. This alarming statistic underscores the tangible financial burden imposed by rising interest rates, diverting an increasing portion of taxpayer money towards servicing existing debt rather than funding essential public services or new policy initiatives. The UK’s situation is compounded by a complex interplay of factors including the lingering economic effects of the COVID-19 pandemic, the ongoing impact of Brexit on trade and investment, and the recent energy crisis, all contributing to a challenging fiscal landscape.
Across the Atlantic, the world’s largest economy, the United States, is also grappling with its own monumental debt challenge. The US national debt has now surpassed an unprecedented $40 trillion, a staggering sum that has effectively doubled within the space of just a decade. This rapid accumulation of debt has triggered widespread concerns, both domestically within the US political and economic spheres, and internationally among global financial institutions and trading partners. The sheer scale of US debt raises fundamental questions about its long-term sustainability, its potential to crowd out private investment by increasing demand for capital, and its implications for the global financial system, given the dollar’s pre-eminent role as the world’s primary reserve currency. The continuous need for the US Treasury to issue new debt can put upward pressure on global interest rates, affecting borrowing costs for other nations and international markets.
Speaking on the sidelines of the prestigious United Nations General Assembly, Kristalina Georgieva reiterated the IMF’s unequivocal message to advanced economies: while certain profound economic factors, such as geopolitical conflicts and commodity price volatility, may indeed lie beyond the immediate control of individual governments, these nations retain significant command over their domestic economic policies. This distinction highlights the critical importance of internal reforms and fiscal discipline.
Georgieva outlined two paramount actions that must be undertaken with immediate effect. "There are these two things that must be done: bring debt levels down, put fiscal consolidation as a priority, and make sure that the central banks deliver on their mandate for price stability," she declared. Fiscal consolidation, in this context, refers to a set of policies aimed at reducing government deficits and debt accumulation. This typically involves a combination of revenue-enhancing measures, such as tax increases or reforms, and expenditure-reducing measures, including cuts to public spending. These decisions are inherently politically charged and often unpopular, demanding considerable resolve from elected officials. Simultaneously, central banks bear the crucial responsibility of maintaining price stability, primarily through managing interest rates and monetary policy, to curb inflation without unduly stifling economic growth. The tightrope walk between these objectives requires careful calibration and robust independence from political pressures.
"It is impossible to stress strongly enough how critical it is to get the courage to take the steps that are necessary. These are politically tough steps to take, but necessary steps to take," Georgieva emphasized, acknowledging the inherent political difficulties associated with implementing austerity or revenue-raising measures. Such policies can evoke public resistance, electoral consequences, and social unrest if not managed carefully and communicated effectively. However, the IMF’s view is that delaying these actions will only exacerbate the problem, leading to even more drastic and painful adjustments in the future.
When pressed specifically on the UK’s comparatively higher interest costs relative to some other major economies, Georgieva offered a nuanced perspective. She stated that the UK’s position was "not very different" from that of many other developed nations currently grappling with similar inflationary pressures and post-pandemic fiscal challenges. This suggests that while the UK faces specific domestic hurdles, its predicament is part of a broader global trend. She commended "fairly consistent action" by the UK government towards lowering debt and lauded specific planning and housing reforms. These reforms, she suggested, are crucial because advanced economies "don’t have the cash" for substantial growth-boosting fiscal stimuli and must, therefore, increasingly rely on structural reforms to foster an environment conducive to private sector investment and productivity gains. Such reforms can include deregulation, improvements to infrastructure, and policies that enhance labor market flexibility, all designed to unlock economic potential without adding to the national debt.
At the heart of government financing lies the bond market. Governments around the world raise the capital they need to fund their operations and investments by issuing and selling bonds. These bonds are essentially a form of "IOU" – a promise to repay a borrowed sum (the principal) at a future date, along with regular interest payments, to the investment funds, pension funds, and other institutional investors that purchase them. The interest rates paid on these bonds, known as yields, have been on a significant upward trajectory in recent months. This rise is largely driven by mounting concerns among investors that high and persistent inflation will erode the real value of their returns, diminishing their purchasing power over time. Consequently, investors demand higher yields as compensation for this inflation risk.
However, inflation is not the sole factor contributing to the surge in bond yields. Other powerful forces are also at play. Central banks, for instance, are actively engaging in quantitative tightening (QT), a process where they reduce their holdings of government bonds, thereby decreasing demand and putting upward pressure on yields. This unwinds years of quantitative easing (QE) policies designed to stimulate economies. Furthermore, a novel and increasingly significant factor is the escalating competition in the bond market itself. Large technology companies, with their immense capital requirements, are aggressively seeking to raise colossal sums of money to invest in the burgeoning field of artificial intelligence (AI) development. This competition for capital from the private sector, particularly from high-growth, high-demand areas like AI, can draw investment away from government bonds, compelling governments to offer more attractive yields to secure necessary funding.
Intriguingly, Georgieva also connected the rapid advancements in AI to potential financial stability concerns. Referencing recent widespread apprehension about the potential "loss of safe control" over such sophisticated systems, she posited that this could emerge as a significant financial stability problem, alongside the already pressing issue of spiralling debt levels. "If we see more incidents when AI takes [on a] life of its own, then we can be faced with a significant financial stability risk," she warned. This highlights a growing awareness within the IMF that technological disruptions, particularly those as transformative and potentially unpredictable as advanced AI, can introduce new and complex risks to the global financial architecture. These risks could manifest as market volatility, systemic failures if critical financial infrastructure becomes over-reliant on uncontrolled AI, or even broader economic instability if AI leads to massive job displacement without adequate societal adjustment.
The IMF’s managing director reiterated the influential body’s overarching assessment that the global economy is currently being shaped by two formidable forces, paradoxically "pushing in opposite directions." On one hand, there is the persistent and damaging energy price shock, largely a consequence of geopolitical tensions and supply disruptions. On the other, there is the transformative and potentially growth-enhancing wave of investment in artificial intelligence. Resolving the energy crisis remains paramount for global economic stability.
Georgieva specifically emphasized the critical importance for the "low exports of oil and gas from the Gulf to resume in a durable manner" for the energy supply shock to finally recede into the "rearview mirror." A sustained and reliable flow of energy supplies from major producers is vital for stabilizing global energy markets, reducing inflationary pressures, and supporting industrial activity worldwide. "That is a very significant step to normalisation," she concluded, acknowledging, however, that despite hopes and efforts, such a durable resolution has yet to materialize. The confluence of these complex challenges – spiralling debt, high inflation, geopolitical instability, and the transformative yet risky rise of AI – underscores the urgent need for decisive and courageous action from policymakers globally to steer the world economy towards a more stable and prosperous future.

 Roy Suryo
 George Anjay